

 1 week ago
9
PROTECT YOURSELF with Orgo-Life® QUANTUM TECHNOLOGY
Orgo-Life the new way to the future Advertising by Adpathway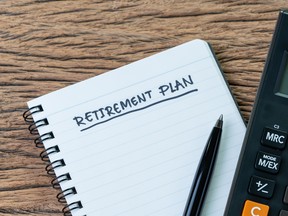
Article content
Joseph* and Natalie,* both 56, are soon-to-be empty nesters and retirement is in sight. Aside from contributing to Joseph’s employer-managed retirement pension plan, this is the first time they have been able to put aside extra money for the future.
THIS CONTENT IS RESERVED FOR SUBSCRIBERS ONLY
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman, and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
SUBSCRIBE TO UNLOCK MORE ARTICLES
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
REGISTER / SIGN IN TO UNLOCK MORE ARTICLES
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account.
- Share your thoughts and join the conversation in the comments.
- Enjoy additional articles per month.
- Get email updates from your favourite authors.
THIS ARTICLE IS FREE TO READ REGISTER TO UNLOCK.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account
- Share your thoughts and join the conversation in the comments
- Enjoy additional articles per month
- Get email updates from your favourite authors
Sign In or Create an Account
or
Article content
“For a long time it was a struggle to meet expenses, but within the past two years it’s become easier,” said Joseph. “Our only debt is a mortgage and car loan. We want to start investing what we can to make sure we are comfortable when we retire.”
Article content
Article content
Advertisement 1
Article content
The couple has a combined annual income of $115,000 before tax. Joseph’s registered pension plan (RPP) from a former employer is valued at $300,000. It is currently invested in an index-based mutual fund designed for investors planning to retire around 2035. He also has $500 in a registered retirement savings plan (RRSP) and $5,000 in a tax-free savings account (TFSA). Natalie has about $2,000 to $3,000 in her newly formed employer RPP.
Article content
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
Article content
While both Joseph and Natalie are planning to retire at 65, ideally they would like to do so at age 62 or 63. They wonder if this is possible. And if so, how? And if they have to work until age 65, what can they do now to ensure they will have enough to meet their cash flow needs?
Article content
The couple live in Ontario and their home is valued at about $700,000. They have a mortgage of approximately $198,000 which costs them $600 biweekly. They also have a $21,000 car loan. Their average total monthly expenses are $4,500.
Article content
When they retire, Joseph and Natalie plan to sell and downsize, preferably in a small community and at a lower price point so they can be mortgage free and direct any excess money to their savings. Joseph will likely take on part-time work after he retires, but doesn’t want to have to work to pay the bills.
Article content
Advertisement 2
Article content
They would like advice on the investment opportunities available to them, when they should start Canada Pension Plan (CPP) and Old Age Security (OAS) benefits, and how much money they need to generate in retirement.
Article content
Article content
“We don’t have a specific target income goal in retirement,” said Joseph. “We want enough to allow us to live a life of relative ease.”
Article content
What the expert says:
Article content
“Like many Canadians, Joseph and Natalie are doing most of their saving in the final 10 to 15 years before retirement when debt tends to decline, careers advance and child-related expenses fall away,” said Eliott Einarson, a retirement planner at Ottawa-based Exponent Investment Management.
Article content
“Their modest retirement needs put them on track for retirement at 65. However, to understand what is possible, they need a retirement plan to identify opportunities, test scenarios and guide their next steps.”
Article content
Joseph and Natalie’s first step is to review their current spending and identify what may change in retirement so they can estimate their after-tax income needs. They should also determine whether they can increase retirement contributions or accelerate debt repayment over the next nine years.










 English (US) ·
 French (CA) ·
 French (FR) ·