

 5 hours ago
5
PROTECT YOURSELF with Orgo-Life® QUANTUM TECHNOLOGY
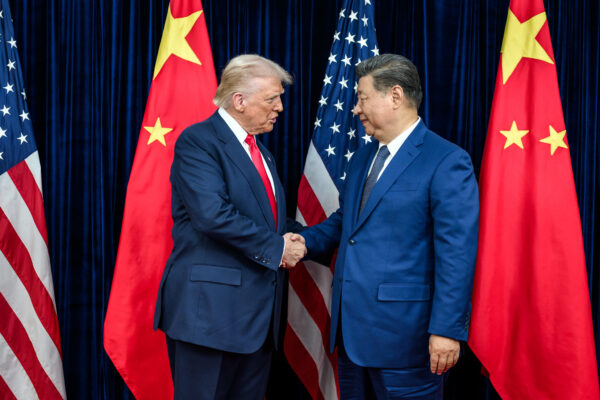
Orgo-Life the new way to the future Advertising by AdpathwayRare earths entered the Trump-Xi summit before the two leaders even sat down. On September 21, two days before President Xi Jinping’s arrival in the United States, China’s Foreign Ministry faced a series of questions on whether Beijing had “fully resumed rare earth deliveries,” whether a “November 10 deadline or expanded restrictions on rare earth exports” could be extended, and whether rare earths controls involving Japan would feature in the Washington talks. The responses were deliberately cautious: Beijing reiterated its commitment to “keeping the global industrial and supply chains of critical minerals safe and stable,” but emphasized that dual-use exports would remain subject to legal and security considerations.
The Foreign Ministry’s responses captured the central paradox of the summit: it may temporarily ease anxiety over rare earth supplies, but it is unlikely to lower the political and regulatory threshold for access.
In April 2025, China’s Ministry of Commerce and General Administration of Customs placed several medium and heavy rare earth elements – including samarium, gadolinium, terbium, dysprosium, lutetium, scandium, and yttrium – under export controls. Exporters of these items are required to apply for licenses, with the stated legal basis including China’s Export Control Law and regulations on dual-use items. This does not amount to a blanket ban on exports, but it does shift rare earth access from a purely commercial transaction to a regulated process shaped by licensing, end-use review, and national security considerations. Once such controls are embedded in a legal and bureaucratic system, they are not easily removed. A summit can improve predictability, but it will not result in the dismantling of China’s carefully built legal framework for export controls.
The same logic applies on the U.S. side. Even if the summit reduces short-term pressure, Washington is unlikely to abandon its effort to diversify away from China-centered critical mineral supply chains. In January 2026, the White House framed U.S. dependence on imports of processed critical minerals and their derivative products as a national security concern, noting that even where the United States has domestic mining capacity, it often lacks sufficient downstream processing capacity. The policy response has therefore gone beyond asking China for more predictable deliveries. The United States is investing in domestic processing, recycling and alternative supply chains, while also working with allies and partners to reduce exposure to single-source dependence. In this sense, any relief produced by the summit may buy some time, but it will not weaken Washington’s broader push for supply-chain diversification.
Rare earths occupy this strategic space because they are not simply another category of traded minerals. Their importance lies less in the raw materials themselves than in the capabilities of the downstream industries they support: high-performance magnets, electric vehicles, wind turbines, advanced electronics and defense systems. This gives rare earths a dual character. They are commercial inputs for global industries, but they are also strategic enablers for military and technological power.
Once a commodity acquires this dual-use profile, access to it is unlikely to be governed by market logic alone. For China, this strengthens the case for licensing and end-use scrutiny. For the United States, it reinforces the argument that dependence on China-centered supply chains is not merely an economic risk, but a strategic vulnerability. Rare earths can be discussed at the summit but the underlying strategic issues are not easily resolved.
This creates an asymmetric form of interdependence. China does not control every part of the global rare earth supply chain, but its position in processing and export licensing gives it a more immediate ability to shape access. The United States is not without options, but its alternatives require time: new processing capacity must be built, recycling systems expanded, and supply arrangements with allies and partners made commercially viable. This mismatch between China’s immediate leverage and the United States’ long-term adjustment capacity creates bargaining space, but not enough for a full reset. The result is a prolonged period of managed vulnerability on rare earths.
Where the summit could still matter lies in the management of risk. Neither side benefits from an uncontrolled shock to the rare earths market. China wants to preserve its right to screen sensitive exports, but it also has an interest in presenting itself as a stable supplier of critical minerals. The United States, meanwhile, wants to reduce dependence on China-centered supply chains, but it also needs time to build alternatives. This creates room for limited accommodation: clearer licensing procedures, smoother civilian trade, and more regular communication over end-use concerns. Yet these would be instruments of crisis management rather than signs of strategic convergence. The summit may reduce uncertainty over how the rules are applied, but it is unlikely to change the rules themselves.
The Trump-Xi summit, therefore, should not be read as a turning point in rare earth politics. Its significance lies less in changing the direction of policy than in clarifying the limits of what diplomacy can achieve. For Beijing, rare earths will remain a strategic resource subject to state control. For Washington, any temporary easing will not remove the underlying concern that dependence on China-centered supply chains creates long-term strategic exposure.
This is the meaning of relief without a resolution. In the emerging logic of China-U.S. geoeconomic competition, critical minerals are instruments of leverage, symbols of vulnerability, and test of strategic resilience.











 English (US) ·
 French (CA) ·
 French (FR) ·